Get Fast Life Insurance Quotes
Compare leading providers and protect your family in minutes. Guided by a licensed agent serving families in multiple states.
Compare top carriers
Shop brands you already trust and see options from a dozen companies side by side.
- Compare 10+ carriers
- Best for shopping around
- Coverage from small to very large
Covered in minutes
Apply online and get an answer fast, with no medical exam for most applicants.
- No medical exam for most
- Decisions in minutes
- Best when you want it done today
Built for ages 50 and up
Whole life and final expense coverage designed to be easier to qualify for later in life.
- Ages 50 to 85
- Health history friendly
- Coverage that never expires
Not sure which one? Let Agent Kamica Assist You
A few short questions and a licensed agent tells you which path fits. No cost, no obligation.
Your information is protected. Never sold or passed to lead buyers, no call centers, and used only to bring you quotes. Sent over an encrypted connection. Privacy Policy.
A quick side by side
| Feature | Policygenius | Ethos | Senior Life |
|---|---|---|---|
| Speed | Shop and compare, usually a few days | Approval in minutes | Days, with agent help |
| Medical exam | Sometimes required | Usually not required | Usually not required |
| Company choice | Compare many brands | Ethos products | Senior Life products |
| Typical age range | Adults of any age | Adults under about 65 | Ages 50 to 85 |
| Policy type | Term and permanent | Mostly term | Whole life and final expense |
| Best for | Shopping the widest market | Getting covered today | Later life and health history |
Swipe the table sideways to see all three
Protect your Georgia business
Three of the most common policies for small businesses. Get a quote online in minutes, no calls, no waiting.
General Liability
Covers the everyday risks of doing business with customers and the public.
- What it covers
- Bodily injury, property damage, and advertising injury claims.
- Who usually needs it
- Contractors, retailers, cleaners, and most service businesses.
Commercial Property
Protects the place you work and the equipment inside it.
- What it covers
- Buildings, inventory, equipment, and tools damaged by fire, theft, or storms.
- Who usually needs it
- Shop owners, offices, restaurants, and anyone with business assets.
Professional Liability
Covers claims that your advice or services caused a client to lose money.
- What it covers
- Mistakes, missed deadlines, and negligence claims, plus legal defense costs.
- Who usually needs it
- Consultants, agents, designers, and other service professionals.
A quick side by side
| Feature | General Liability | Commercial Property | Professional Liability |
|---|---|---|---|
| Protects against | Customer injury and property damage claims | Damage to your place and your things | Claims that your work or advice caused a loss |
| What it covers | Bodily injury, property damage, advertising injury | Buildings, equipment, inventory, tools | Mistakes, missed deadlines, negligence |
| Legal defense | Usually includes defense costs | Not the focus | Usually includes defense costs |
| Who usually needs it | Contractors, retailers, cleaners | Shop owners, offices, restaurants | Consultants, agents, designers |
| Often asked for by | Landlords and clients | Lenders and landlords | Clients and contracts |
| Best for | Everyday customer risk | Protecting what you own | Advice and service work |
Swipe the table sideways to see all three
What each policy type actually does
Most people need exactly one of these. Knowing which one before you talk to anybody puts you in a much stronger position.
Term life
Protection for a set number of years, usually ten to thirty. Simple, affordable, and the right answer for most working families. If you outlive the term, it ends with no payout.
Whole life
Permanent coverage with a fixed premium and a cash value that grows over time. Costs more than term for the same death benefit, and it is there for life.
Universal life
Permanent coverage where you can adjust what you pay and how much coverage you carry within limits. Worth understanding carefully before you sign.
Indexed universal life
Cash value tied to the performance of a market index, with a floor that limits losses and a cap that limits gains. Ask to see the guaranteed numbers, not only the projected ones.
Final expense
Smaller whole life policies meant to cover a funeral and last bills. Built for later ages and for people whose health history makes other policies difficult.
Not sure which?
Almost nobody walks in knowing. Send Kamica your details in the Agent Assistance section above and she will tell you which of these fits your situation, and why.
"I have a health condition. Will I even qualify?"
Most people assume the answer is no and never apply. Often it is yes, at some price, from some company. High blood pressure, high cholesterol, controlled diabetes and treated sleep apnea are commonly approved, and a cancer history is frequently approved once enough time has passed. What you pay depends on the condition, how well it is controlled, and how recent it is.
What matters more is that companies disagree with each other enormously on health history. One company's decline is another's best rate. That is not a sales line. Each insurer builds its own approval tables from its own claims experience, and they weigh the same condition differently.
Which means comparing companies matters more when you have a health history, not less. Applying to one company and treating their answer as the whole market's answer is one of the most expensive mistakes in this category. Some conditions do lead to a decline everywhere, and Kamica will tell you that straight rather than string you along.
Your coverage through work is probably not enough
Group life from an employer is typically one to two times your salary. Against the ten to twelve times income that most planning guidelines suggest, that is a fraction, and it is the reason many families who believe they are covered are not.
It also usually ends the day the job does. There is often an option to keep it, but that option is frequently more expensive than a personal policy a healthy person could buy on their own, and job loss tends to arrive alongside other financial stress. Treat coverage at work as something extra on top of a policy you own and control.
Six mistakes that cost families money
Every one of these is common, and every one is avoidable before you sign anything.
Naming a child as beneficiary
Insurers cannot pay a death benefit directly to a minor. The money goes into a court supervised arrangement that costs time and legal fees, and the child receives whatever is left at eighteen. Name a trust or an adult custodian instead.
The ex-spouse still listed
The beneficiary form controls, not your will. A named ex-spouse is frequently paid regardless of what the will says or what the divorce intended. Review your beneficiaries after any marriage, divorce or birth.
Shading the application
For the first two years the insurer can review a claim over anything material you left out. Understating tobacco use or omitting a condition to save money can undo the policy exactly when your family needs it. Companies check prescription records anyway.
Naming your estate
A benefit paid to a named person passes outside probate, quickly and usually free of income tax. Paid to your estate, it enters probate, becomes reachable by creditors, and can take months. Always name people.
Buying only what is cheapest
The lowest first year price is not the same as the best policy. Ask whether the premium is guaranteed level for the whole term, and whether you can convert to permanent coverage later without a new exam.
Waiting for a better time
Price is set by your age and your health on the day you apply, and both move in one direction. Every year you wait costs more, and a new diagnosis can close doors that are open today.
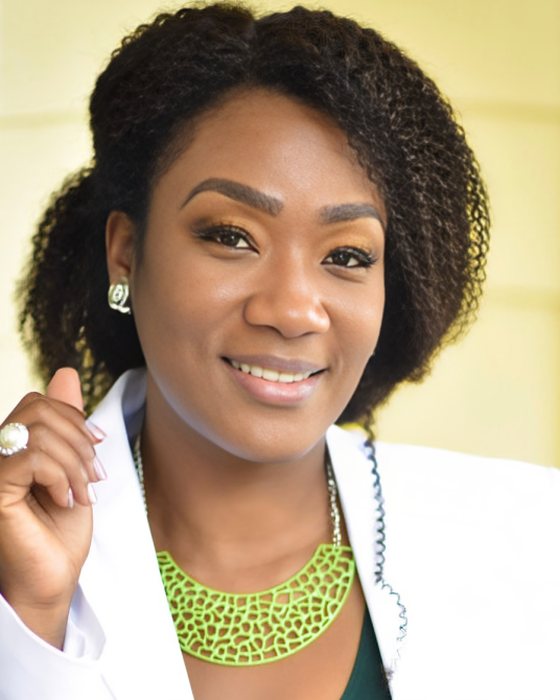
"Most people put this off because they think it is expensive and complicated. It is usually neither. My job is to show you what is out there and let you decide."
Kamica Goins, Licensed Life Insurance Agent
Truvelocity LLC, Buford, Georgia
Licensed in multiple states
What people ask first
Straight answers to the questions that come up in almost every first call.
How much life insurance do I actually need?
The common starting point is ten to twelve times your annual income. Then adjust it: add what is left on the mortgage, any other debt that would not disappear, and what you want set aside for each child's education. Subtract coverage you already have and savings your family could reach.
That gives you a working number, not a rule. A single earner with young children and a large mortgage needs more than a dual income household with the house nearly paid off.
How much does it cost?
Four things set the price: your age, your health, how much coverage you buy, and how long the coverage lasts. Age and health matter most, and both only move in one direction, which is why waiting costs money.
Most people overestimate the cost, often by a wide margin. Tell Kamica a monthly number you are comfortable with and she will show you what that actually buys before you commit to anything.
What is the real difference between term and whole life?
Term covers you for a set number of years and pays only if you die during that window. It buys the most protection per dollar, which is why it fits most families with children and a mortgage.
Whole life covers you for as long as you keep paying and builds a cash value you can borrow against. It costs considerably more for the same death benefit. It makes sense when you want coverage that never expires, help with final expenses, or a long term savings component you control.
Neither is better in the abstract. The right one depends on whether your need has an end date.
Will I have to take a medical exam?
Often no. Many companies now decide on health questions, prescription history and a short phone interview alone. Larger amounts of coverage and older applicants are more likely to be asked for an exam.
If one is required, the company pays for it and a nurse comes to your home or office at a time you pick. It is usually height, weight, blood pressure, a blood sample and a urine sample, and it takes about twenty minutes.
How long does it take to get covered?
It ranges from the same day to about six weeks. Companies using instant approval can issue a policy in minutes for applicants who qualify. Applications that need medical records from your doctor or a paramedical exam take the longest, because the wait is on the records, not the insurer.
Answering the health questions accurately and completely the first time is the single biggest thing you control on speed.
Is the money my family receives taxed?
A life insurance death benefit paid to a named beneficiary is generally not treated as taxable income under federal law. That is the main reason it lands intact when a family needs it.
Two exceptions worth knowing. If the insurer holds the money and pays interest before releasing it, that interest portion is taxable. And if the policy is considered part of your estate, estate tax can apply, which mostly affects larger estates. Ask a tax professional about your own situation.
How long does it take for my family to actually get paid?
Usually somewhere between two weeks and two months once the insurer has the complete claim packet, which is typically a certified death certificate, the claim form, and proof of the beneficiary's identity. Incomplete paperwork is the most common cause of delay.
One thing to expect: if the policy is less than two years old, the insurer reviews the original application before paying. That is standard, and it adds time.
What happens if I miss a payment?
Policies include a grace period, most commonly thirty or thirty one days, and some longer. The policy stays in force during it. If someone dies during the grace period, the death benefit is still paid, with the unpaid premium deducted from it.
If the grace period runs out, the policy lapses. Most companies allow reinstatement within a set window, though that can mean answering health questions again and paying what was missed. Set the premium on autopay and this never comes up.
Can I change my mind after I buy?
Yes. Every policy comes with a free look period that starts when you receive it. Cancel within that window and you get every dollar of premium back, no questions asked and no penalty.
Georgia law sets the minimum at ten days. Other states run from ten up to thirty, and some companies give longer than their state requires. The exact number is printed on the first pages of your policy, so check it when the packet arrives.
How long after quitting nicotine do I qualify for non tobacco pricing?
It depends heavily on the company. Some will give non tobacco rates after twelve months clean. Many require a full twenty four months. A few want three to five years before their best classes open up.
This is one of the clearest cases where shopping several companies is worth real money, since the same quit date can land in completely different price brackets. Be accurate about your quit date either way, because exams test for nicotine byproducts.
Can I change my beneficiary later?
Yes, as often as you want, by filing a change form with the insurer. The only exception is an irrevocable designation, which is uncommon and usually tied to a divorce agreement or a business arrangement.
Worth knowing: the beneficiary form controls, not your will. A named ex-spouse gets paid regardless of what the will says. Review it after any marriage, divorce, birth or death in the family.
Should a stay at home parent be covered?
Yes, and it is one of the most commonly skipped policies. The work does not stop when the person doing it is gone. Childcare, transportation, cooking, and household management all become things a surviving spouse either pays for or leaves a job to cover.
Insurers understand this and will issue coverage on a non earning spouse, usually up to a limit tied to the working spouse's coverage.
What if my insurance company goes out of business?
Every state runs a guaranty association that steps in when a licensed insurer fails. In most states the protection covers at least three hundred thousand dollars in death benefit and one hundred thousand in cash surrender value, and limits vary by state.
It is still worth asking about a company's financial strength rating before you buy, especially for permanent coverage you expect to hold for decades.
Ready to see your options?
Free to compare, no obligation, and no Social Security number needed to get started.
This page is general education, not financial, tax or legal advice. Product features and availability vary by state, age, health and company approval. Confirm any specific policy detail with the company's own documents before you buy.